
Choosing between a French subsidiary or branch is rarely a paperwork question. If you run a company outside France and you are weighing a presence here, another question comes first. What happens to your profit the day it is earned, and how much of it do you actually keep?
25%
0
3
Default withholding on a branch’s presumed distribution
Euros that need to actually leave France for it to apply
Situations where the withholding does not apply
French subsidiary or branch: two structures, two outcomes
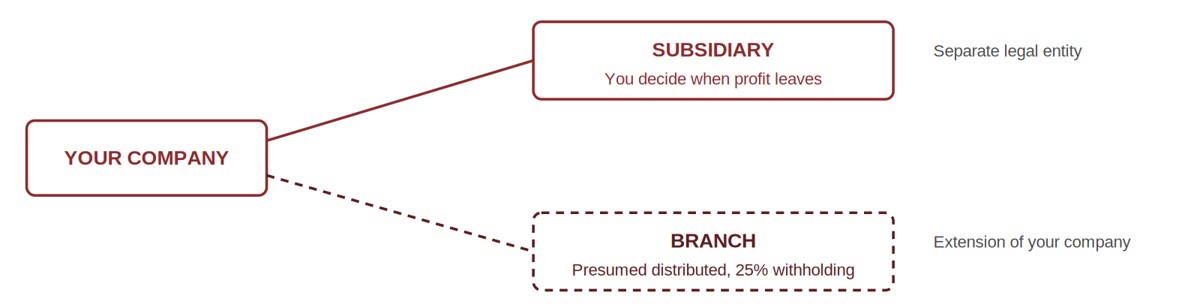
A subsidiary is a separate legal person under French law. It carries its own liability, its own accounts and its own governance, even when your company owns every share of it. A branch, by contrast, carries none of that separation. Instead, it operates as an extension of the company you already run. As a result, your parent company remains fully liable for what happens here.
Subsidiary, its own legal identity
SARL, SAS or SA. Liability stays inside the French entity. More independence, more setup, its own accounts and governance.
Branch, an extension of you
No separate personality, no share capital required. Faster to open, but every obligation flows back to the parent company.
Subsidiary vs branch in France at a glance
The table below sums up the main differences. In practice, each line deserves a check against your own situation and the tax treaty with your home country.
| Criteria | Subsidiary | Branch |
|---|---|---|
| Legal personality | Yes. A separate French company (SAS, SARL or SA). | No. The branch is part of the foreign company. |
| Parent company liability | In principle, limited to its contribution to the share capital. | Full. The parent answers for every commitment made in France. |
| Taxation of French profit | French corporate tax on the subsidiary’s own profit. | French corporate tax on the profit of the French activity. |
| Withholding tax on profit | Only when a dividend is paid. The EU Parent-Subsidiary Directive (article 119 ter of the French tax code) or a tax treaty can remove or reduce it. | Profit presumed distributed every year (article 115 quinquies of the French tax code), unless the EU or EEA exemption or a tax treaty applies. |
| Accounting and filing | Full French annual accounts, approved and filed with the commercial register. | Separate accounts of the French activity, used to determine French taxable profit. Registration with the French commercial register. |
| Setup effort | Heavier: articles of association, share capital, governance. | Lighter: no articles or share capital of its own, but documents from the parent are required. |
| Reporting to the parent | Own accounts, then reported or consolidated at group level. | French figures feed directly into the parent company’s own accounts. |
On corporate tax, both forms are equal
Let’s clear up a common assumption first. Whether you open a subsidiary or a branch, profit made in France is subject to French corporate tax, as soon as the foreign company is a capital company. Therefore, the real difference does not play out on the tax rate. Instead, it plays out on what happens to the profit afterwards.
The French branch tax, the real difference
A subsidiary’s profit only reaches the parent company when you choose to pay a dividend. In other words, you stay in control of the timing.
A branch, however, works the other way. Profit made in France by a foreign company is presumed distributed, every year, to shareholders who have neither their tax residence nor their registered office in France. You decided nothing. Even so, the tax authority treats the money as having left the country. This rule comes from article 115 quinquies of the French tax code, often called the French branch tax.
For example, your branch generates 100,000 EUR in profit. Corporate tax takes its share first. The remainder is then presumed distributed and carries a 25% withholding, even when not a single euro has actually left France.
Three situations where it does not apply
- Your place of effective management sits in the European Union or the European Economic Area, and you pay corporate tax there. In that case, the withholding disappears, even where a tax treaty would have said otherwise, as the French tax administration’s guidance confirms.
- The tax treaty between France and your home country removes or reduces it. This is common. However, it is never automatic.
- Your actual distributions are lower than the amounts taxed. In that case, you request a new assessment.
Beyond tax: liability, staff and reporting
Tax is only one part of the decision. Liability, staff and reporting also differ, and they often weigh more over time.
Liability. With a subsidiary, the parent’s exposure is in principle limited to its contribution to the share capital. With a branch, however, the foreign company answers for every commitment made in France.
Staff. People hired to work in France generally fall under French employment law, whichever structure you choose. With a branch, though, the employer is the foreign company itself.
Reporting. A subsidiary keeps its own French accounts, which your group then reports or consolidates. A branch keeps separate accounts of its French activity, so that its French taxable profit can be determined. In both cases, your parent company expects French figures in its own format and on its own calendar. This is exactly what our group reporting service for French subsidiaries of foreign groups covers.
Setting up a subsidiary in France: what it involves
Setting up a subsidiary in France means incorporating a full French company. First, you choose its legal form. An SAS leaves wide freedom in drafting the articles of association, while an SARL follows a more structured legal framework. Then, you draft the articles, contribute the share capital and appoint the managers. Finally, the company is registered through the French online one stop shop for business formalities.
A foreign company opening a branch follows a lighter path, since the branch has no articles or capital of its own. Even so, the branch is registered with the French commercial register through the same portal. For this, the parent provides its own documents, such as a certified copy of its articles and a recent extract from its home registry.
The one question to settle before you open
A single question conditions everything else. Where is your place of effective management, and what does the tax treaty between France and that country provide? Depending on the answer, a branch is a light and neutral solution. Otherwise, it creates friction on every euro earned in France. That is why the choice between a French subsidiary or branch should follow this analysis, not precede it.
How we work with you before you file anything
Most firms hand you a checklist of registrations and move on. We start by understanding your business, your reporting obligations toward your parent company, and your plans for the French market over the next three to five years. Only then do we recommend a structure, because the paperwork is the easy part. Getting the structure wrong, or missing the tax treatment attached to it, is the expensive part.
At CREO Conseils, we support directors running multiple structures: holding companies, real estate companies and operating entities. A French branch attached to a foreign company follows the same logic. It never exists on its own, so its taxation always has to be read alongside the head office.
Running your French entity from a distance
Once the entity exists, the real work is keeping it visible to you without requiring your presence. In practice, our clients manage their French operations with real time access to figures, documents and key indicators from wherever they are. The tool, however, is not the service. What matters is that someone on our team reviews the numbers, flags what needs your attention, and reports back in a format your parent company can use directly.
A short glossary
Subsidiary
A separate French legal entity, majority or fully owned by a foreign parent company.
Branch
A French extension of a foreign company, with no separate legal personality and full liability resting on the parent.
Liaison office
A non commercial presence in France, used for representation rather than trading activity.
French subsidiary or branch: frequently asked questions
Tax questions
Is a French branch taxed differently from a French subsidiary?
Both pay French corporate tax on the profit made in France. The difference comes afterwards. A subsidiary’s profit leaves France only when a dividend is paid. A branch’s profit, by contrast, is presumed distributed every year under article 115 quinquies of the French tax code.
What is the French branch tax?
It is a withholding tax on the after tax profit of a French branch of a foreign company. This profit is presumed distributed to shareholders based outside France. By default, its rate follows the standard corporate tax rate, currently 25%. However, a tax treaty or the EU and EEA exemption can remove or reduce it.
Does a company based in the EU pay the French branch tax?
Generally not. The presumption does not apply when the company’s place of effective management is in the EU or the EEA, and it is subject to corporate tax there without exemption. Even so, the company must be able to prove it, for example with a certificate of tax residence.
Do dividends paid by a French subsidiary bear withholding tax?
They can. Dividends paid to a foreign parent may bear French withholding tax. However, a parent company based in the EU, or in certain EEA states, can be exempt under article 119 ter of the French tax code, which applies the EU Parent-Subsidiary Directive. Among other conditions, it must hold at least 10% of the capital for at least two years. Otherwise, the applicable tax treaty may reduce the withholding.
Liability and setup questions
Is the parent company liable for the debts of its French branch?
Yes. A branch has no legal personality of its own. Consequently, the foreign company answers for all commitments made in France. With a subsidiary, the parent’s exposure is in principle limited to its contribution to the share capital.
Which is faster to set up, a subsidiary or a branch?
A branch is usually lighter to open, because it needs no articles of association or share capital of its own. Still, it must be registered with the French commercial register, with documents from the foreign parent. A subsidiary, on the other hand, requires incorporating a full French company.
Preparing a French implantation, or already running a branch without having checked this?
Book a scoping call and we will qualify your situation together, before it costs you on the next distribution.